
S&P 500 futures were little changed in early trading Tuesday, as investors awaited results from major technology and industrial companies. Monday's recovery provided some relief after last week's selling, but earnings now need to give bidders more evidence that growth can justify valuations, which remain elevated by historical standards. The market is looking for confirmation that corporate profitability can keep pace with the expectations embedded in current prices, and the coming wave of reports will be a critical test of that assumption.
The S&P 500 gained 0.4% to 7,690.73 on Monday, while the Nasdaq Composite climbed 1.1% to 26,430.89. The Dow slipped 0.1%. Advancing indexes overstated the breadth of the recovery: decliners still outnumbered gainers on both the NYSE and Nasdaq, suggesting the rally was narrower than the headline numbers implied. The divergence between the major indexes and the underlying breadth of the market is a reminder that the recovery has been concentrated in a handful of large-cap technology names.
Amazon jumped 5% after Morgan Stanley named it a top pick and raised its target to $350 from $335. Tesla gained 3.8%, while Datadog rose 5.4% following a Bernstein upgrade. The gains in individual names suggested that stock-specific catalysts remained a dominant driver of performance, rather than a broad-based shift in market sentiment. Investors are rewarding companies that can demonstrate clear earnings momentum, while those with less certain prospects are being left behind.
CoreWeave closed 0.4% lower despite a Goldman Sachs Buy upgrade, suggesting financing concerns remain difficult to shake. The divergence between analyst optimism and market price action highlights the uncertainty surrounding the AI infrastructure trade and its ability to generate returns, particularly when borrowing costs remain elevated. The stock's performance is a reminder that analyst ratings alone are not enough to drive sustained gains when the underlying economics of a business remain uncertain.
Outside technology, Cleveland-Cliffs surged 16% after stronger guidance, including expectations for more than $4 billion in adjusted EBITDA next year. Company outlooks are still producing substantial moves across sectors, with individual results driving dispersion in the market and rewarding companies that can demonstrate a credible path to profitability. The strength of the industrial sector is a positive signal for the broader economy, and investors are watching for signs that the recovery is broadening beyond technology.
South Korea's Kospi fell around 3.6%, Japan's Nikkei lost 1.5% and Asia ex-Japan shares declined 0.9%. European futures also weakened, with Euro Stoxx 50 contracts down 0.7%. The global retreat suggested that the recovery in US equities had not yet translated into broader risk appetite, and investors remained cautious about the durability of the rebound. The divergence between US and Asian markets is a reminder that the global economic outlook remains uneven, and any signs of weakness in Asia could weigh on sentiment.
EUR/USD traded near $1.1215, GBP/USD around $1.3305 and USD/JPY near 158.60 yen. France remained a concern: its 10-year yield gap over Germany widened almost 10 basis points Monday to 147.3 basis points, reflecting ongoing political uncertainty and fiscal concerns that could weigh on European risk assets. The widening spread is a reminder that political risk can have a material impact on market pricing, and investors are watching for any signs of further deterioration in the French fiscal outlook.
Brent remained near 110 a barrel as markets weighed possible Russian sanctions relief against Middle East supply risks. Watch contract rollover in WTI: November expires today and traded near $103, versus around $98 for December. Energy prices remain a key input for inflation expectations and corporate margins, and any sustained rise in crude could complicate the central bank's path and weigh on consumer spending. The divergence between Brent and WTI also reflects differences in regional supply and demand dynamics.
Gold traded around $4,140 an ounce, while Bitcoin softened toward $81,500. Higher yields remain a headwind for bullion because it pays no interest. The weakness in precious metals and crypto suggested that the broader appetite for risk assets remained uneven, with investors still cautious about the durability of the equity recovery. The relative strength of equities versus gold and crypto is a reminder that the market's focus remains on growth expectations rather than safe-haven demand.
The US 10-year Treasury yield held near 5.13%, keeping financing costs in focus. Even if the Fed leaves rates unchanged next week, elevated market yields can restrain spending and valuations. The level of yields is a critical factor in the equity market's ability to sustain its recovery, and any further rise could pressure growth stocks that are particularly sensitive to changes in the discount rate. Investors are watching the yield curve for signs of stress that could signal a shift in the economic outlook.
SpaceX and Netflix report after today's close. Analysts expect SpaceX to earn 13 cents a share on $12.8 billion in revenue. Netflix consensus is around 82 cents on $12.9 billion. Watch spending, cash generation and guidance from both companies, as their results will provide important evidence on the health of the technology sector and the sustainability of the current investment cycle. The reports will be a key test of whether the market's optimism about AI and streaming growth is justified. GE Aerospace and General Motors report before the US open, offering evidence on industrial demand and consumer spending. Meta and Tesla follow Wednesday. Their investment plans will help investors assess whether AI and autonomy spending is generating commercial progress fast enough to support continued expansion, which is a central question for the market. The results from these companies will provide a broader picture of the economy's health and the durability of the current expansion.
GE Aerospace and General Motors report before the US open, offering evidence on industrial demand and consumer spending. Meta and Tesla follow Wednesday. Their investment plans will help investors assess whether AI and autonomy spending is generating commercial progress fast enough to support continued expansion, which is a central question for the market. The results from these companies will provide a broader picture of the economy's health and the durability of the current expansion.
Trading Insight
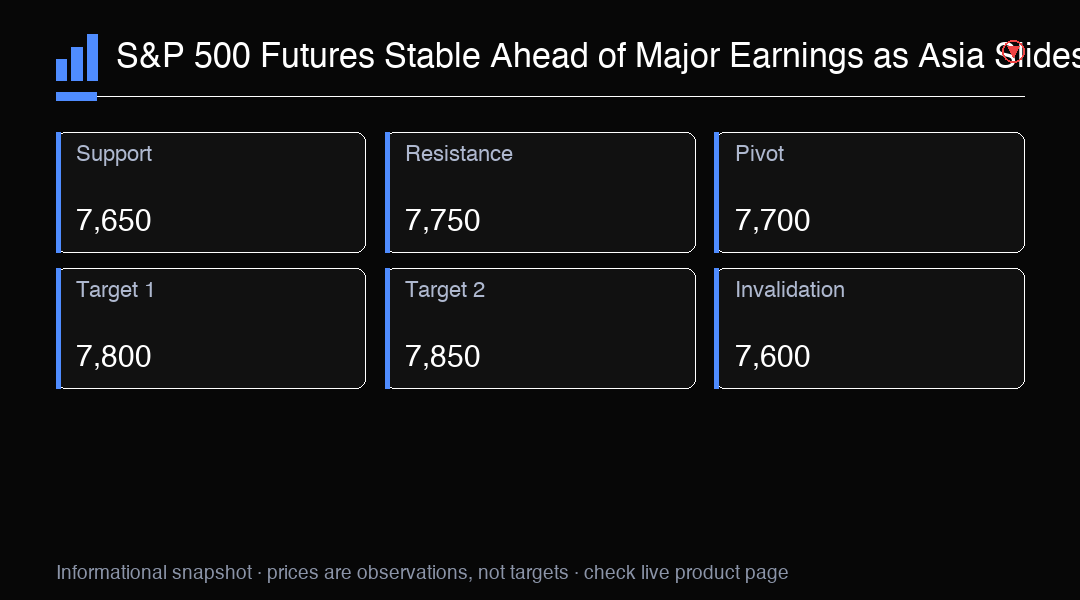
S&P 500 futures were stable at 7,690.73 ahead of major tech earnings. Key support at 7,650. Watch earnings and US data for direction.